Connect with us

Business & Economy

Nigeria’s Inflation Eases Marginally to 15.39% in August — NBS

Published

on

Symbol of Inflation
Share


Nigeria’s headline inflation rate eased marginally to 15.39 per cent in August 2026, from 15.43 per cent in July, according to the latest Consumer Price Index (CPI) report released by the National Bureau of Statistics (NBS) on Tuesday.

The latest figure represents a 0.04 percentage-point decline month-on-month, indicating a slight moderation in the pace of increase in the general price level.

The NBS also reported a significant slowdown in the month-on-month inflation rate, which fell to 0.71 per cent in August, compared with 1.57 per cent in July. This represents a decline of 0.86 percentage points.

According to the statistics agency, the development means that the average prices of goods and services increased at a slower pace in August than they did in July.

Food inflation also recorded a substantial moderation, dropping to 19.57 per cent year-on-year in August 2026, compared with 25.30 per cent recorded in August 2025.

On a month-on-month basis, food inflation declined sharply to 1.02 per cent in August, from 5.56 per cent in July, representing a 4.55 percentage-point reduction.

The NBS attributed the moderation in food inflation largely to changes in the average prices of several food items, including palm oil, carrots, pepper, onions, cassava flour, beef, yam flour, water yam, melon (egusi), fresh ginger, fresh fish, Irish potatoes, wheat grain, frozen chicken and turkey meat, among others.

At the state level, Adamawa recorded the highest year-on-year food inflation rate at 38.85 per cent, followed by Zamfara at 37.96 per cent and Bayelsa at 36.20 per cent.

The lowest year-on-year food inflation rates were recorded in Borno at -4.04 per cent, Jigawa at -0.23 per cent, and Kebbi at 3.47 per cent.

On a month-on-month basis, Katsina recorded the highest food inflation rate at 9.48 per cent, followed by Rivers at 8.86 per cent and Osun at 8.32 per cent.

Meanwhile, the slowest month-on-month food inflation rates were recorded in Taraba at -12.42 per cent, Borno at -12.15 per cent, and Bauchi at -8.88 per cent.

The latest NBS figures point to a broad moderation in the pace of price increases, particularly in the food sector, although inflation remains a major economic concern for households and businesses across the country.


Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business & Economy

Nigeria Open for Business, Tinubu Assures Investors

Published

on

President Bola Ahmed Tinubu
Share


President Bola Tinubu has assured local and foreign investors that Nigeria remains open for business, saying his administration is working to create a more predictable, competitive and investment-friendly environment.

Tinubu spoke on Monday in Abuja at the 75th anniversary celebration of the Nigerian Bottling Company Limited (NBC), where he was represented by the Secretary to the Government of the Federation, Senator George Akume.

The President said the Federal Government was aware of the challenges facing businesses and was addressing them through economic reforms under the Renewed Hope Agenda.

“Our message to investors, both Nigerian and international, is clear: Nigeria is open for business, and we are working to make the business environment more predictable, more competitive and more supportive of investment,” he said.

He identified reliable electricity, infrastructure, clear regulations, efficient ports and logistics, access to foreign exchange and a business-friendly tax system as critical to attracting and retaining investments.

Tinubu said the administration’s economic reforms were aimed at building a more productive economy, reducing dependence on imports, expanding local manufacturing and creating more jobs.

He also welcomed the Coca-Cola System’s planned $1 billion investment in Nigeria over five years, describing it as a vote of confidence in the Nigerian economy.

The President said the government was interested not only in the amount of investment coming into the country but also in its impact on job creation, skills development, local sourcing, technology transfer and the growth of Nigerian businesses.

He urged investors to see Nigeria not merely as a large consumer market but as a production base from which they could serve African and global markets.

Tinubu also commended NBC for its continued investment in production capacity, including new production lines at Asejire in Oyo State and Challawa in Kano State.

He called for greater local content in manufacturing and urged businesses to develop Nigerian suppliers, train young people in technical skills and gradually replace imports with competitively produced Nigerian goods.

The President stressed that government alone could not transform the economy, urging the private sector to invest, innovate, take risks and create jobs.

He also highlighted the importance of human capital development, commending NBC’s Supply Chain Academy, which he said had trained more than 1,400 young people since its establishment in 1996.

Tinubu acknowledged the difficulties caused by the ongoing economic reforms but said Nigeria’s longstanding structural challenges could no longer be ignored.

He assured investors willing to make long-term commitments to Nigeria of the government’s support, particularly those prepared to manufacture locally, develop Nigerian talent, strengthen supply chains and contribute to host communities.

Earlier, the President congratulated NBC on its 75th anniversary, describing its growth from a Lagos-based company established in 1951 into a nationwide enterprise as an example of the opportunities available through long-term investment in Nigeria.

He said the Coca-Cola System generated an estimated $1 billion in value-added economic activity in Nigeria in 2024, supported more than 160,000 livelihoods and purchased about $601 million worth of goods and services from Nigerian suppliers.

Tinubu urged NBC and the Coca-Cola System to sustain their investments, deepen local supply networks and continue developing Nigerian talent as the country works towards a more productive and globally competitive economy.

Continue Reading

Business & Economy

Dangote Refinery Targets Africa’s Largest Company Status by December 2026 — Dangote

Published

on

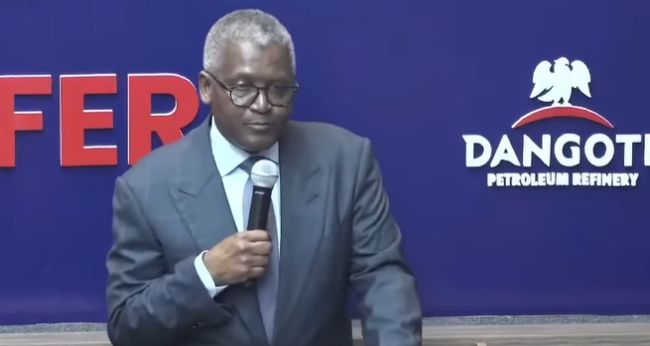
President of Dangote Group, Aliko Dangote
Share


President of Dangote Group, Aliko Dangote, has expressed confidence that Dangote Petroleum Refinery and Petrochemicals FZE will emerge as the most viable and largest company in Africa by the end of December 2026.

Dangote made the declaration on Monday, September 14, 2026, at the trading floor of the Nigerian Exchange (NGX) in Lagos, where he delivered the opening address to formally launch the refinery’s Initial Public Offering (IPO).

The public offer comprises 4.1 billion new ordinary shares priced at ₦525 per share, with a minimum subscription of 10 shares valued at ₦5,250. The offer opened on September 14 and is scheduled to close on October 13, 2026, subject to the terms and conditions contained in the Prospectus.

The IPO is targeted at retail and institutional investors, as well as eligible investors across Africa and other parts of the world, as Dangote Refinery seeks to broaden ownership and deepen participation in Nigeria’s capital market.

Speaking at the event, Dangote urged Nigerians and other investors not to underestimate the potential of the refinery, saying the company was positioned for significant growth and value creation.

“Everything is in the hands of God, but by the end of this year, this is going to be the largest company in Africa, not in Nigeria,” Dangote said.

He described the IPO as an opportunity for investors to participate in the future growth of the refinery, urging prospective shareholders not to miss the opportunity.

According to him, the public offer is not primarily about raising funds for the Dangote Group, but about democratising wealth creation by giving ordinary Nigerians and other investors an opportunity to own a stake in one of Africa’s biggest industrial projects.

Dangote said the decision to open the refinery’s ownership to the public followed a long-standing commitment to ensure that the benefits of the project extend beyond a small group of investors.

He explained that the company waited until the refinery became operational, sustainable and sufficiently de-risked before taking the decision to invite the public to participate in its ownership.

“Today is not about listing a company but about listing a company for Nigerians, for Africa and for the black race,” he said, while inviting investors from across Africa, the Caribbean, Europe, America, China and other parts of the world to become shareholders.

Dangote also highlighted the potential benefits of the investment to Nigerians, particularly teachers, civil servants and parents with children studying abroad.

He said investors could potentially benefit from dollar-denominated dividends, which could provide some protection against the impact of naira depreciation on families with foreign currency obligations.

According to him, the opportunity could give parents with children abroad greater confidence in meeting future school-fee obligations even during periods of currency devaluation.

The Dangote Group president further disclosed that the group currently has about $46 billion worth of projects and investments in its pipeline, aimed at expanding its various businesses and achieving its Vision 2030 objectives.

He stressed that the IPO was therefore not driven by a need for additional capital to execute the group’s projects.

“If it is the question of raising money, I think we have raised more than what we need as a group to execute all our projects,” Dangote said.

The public offer is expected to raise approximately ₦2.15 trillion, potentially making it one of the largest equity offerings ever undertaken in Africa.

The proceeds, according to the company, will be deployed towards the refinery’s long-term growth plans, operational expansion, strategic investments and further value creation for shareholders and other stakeholders.

Dangote also disclosed that the group had previously conducted a private placement as part of its capital-raising strategy.

He said the original plan involved raising $2.5 billion, comprising a $1.5 billion IPO and a $1 billion private placement. According to him, the private placement attracted significant demand, leading the company to allocate and reallocate applications.

Dangote said the company ultimately returned applications worth about $1.2 billion after receiving strong demand during the process.

He explained that the funds raised through the private placement had already met the group’s immediate funding requirements, reinforcing his position that the current IPO is primarily aimed at expanding public ownership and allowing more people to share in the refinery’s future prosperity.

Meanwhile, Nigerian Exchange Group’s Group Managing Director and Chief Executive Officer, Temi Popoola, said the participation process had been designed to be accessible, transparent and technology-enabled.

Eligible investors can subscribe through approved distribution channels, including NGX Invest, designated commercial banks and authorised investment platforms, subject to the requirements contained in the Prospectus.

Dangote said the broader objective was to ensure that the economic benefits generated by the refinery are shared among a wider pool of investors, rather than being concentrated among a limited number of private shareholders.

The development marks a significant step in the evolution of the Dangote Refinery, which has become one of the most prominent industrial investments in Africa and a major component of Nigeria’s ambition to strengthen domestic refining capacity, reduce dependence on imported petroleum products and expand its participation in the global energy market.
Continue Reading

Business & Economy

Oil Prices Rise Above $100 As Iran Tightens Grip On Strait Of Hormuz

Published

on

Crude oil
Share


Oil prices rose above $100 per barrel on Thursday after Iran tightened restrictions on vessels passing through the Strait of Hormuz amid its ongoing war with the United States.

Brent crude, the international benchmark, stood at $101.28 per barrel in early Asian trading, after rising above $100 on Wednesday for the first time since July.

Iran’s Revolutionary Guards said they had attacked several vessels attempting to pass through the strategic waterway, including two US vessels, eight oil tankers and 10 other vessels described as “non-compliant.”

The Strait of Hormuz is one of the world’s most important oil shipping routes, normally carrying about one-fifth of global oil supplies.

The British maritime security agency UKMTO also reported that several merchant vessels in the Northern Arabian Gulf and Gulf of Oman had come under fire amid continuing military activities in the region.

Iran has now expanded its restricted area beyond the Strait of Hormuz, declaring parts of the Gulf of Oman and Arabian Sea a “prohibited zone.” Iranian authorities warned that vessels entering the area without coordination could face sanctions.

US President Donald Trump, however, said oil prices would eventually fall as the war ends. He claimed that the United States was winning the conflict and had control of the Strait of Hormuz.

Trump also suggested that the war could end after the US mid-term elections in November, saying Iran could no longer continue fighting.

However, reports indicate that some US officials privately believe the conflict could continue for much longer.

The Iranian Revolutionary Guards also claimed responsibility for an attack on a US military base in Jordan, describing it as retaliation for US forces destroying five Iranian oil tankers.

Jordan said its military intercepted 18 missiles fired toward the country.

Iran condemned the destruction of its oil tankers, describing the action as a threat to regional and international peace and security. Tehran said its attacks on US military facilities were carried out in self-defence.

The escalating conflict has increased concerns about global energy supplies, particularly if the disruption of shipping through the Strait of Hormuz continues.

Meanwhile, the International Atomic Energy Agency’s Board of Governors voted to refer Iran to the UN Security Council over its nuclear activities. The resolution reportedly passed by 23 votes to three, with eight countries abstaining.

Iran rejected the resolution, accusing the United States of pressuring the nuclear watchdog and insisting that the decision would produce no results.

Israeli Prime Minister Benjamin Netanyahu also maintained that Iran was close to collapse, saying the main objective was to bring down what he described as Iran’s “terror regime.”


Continue Reading